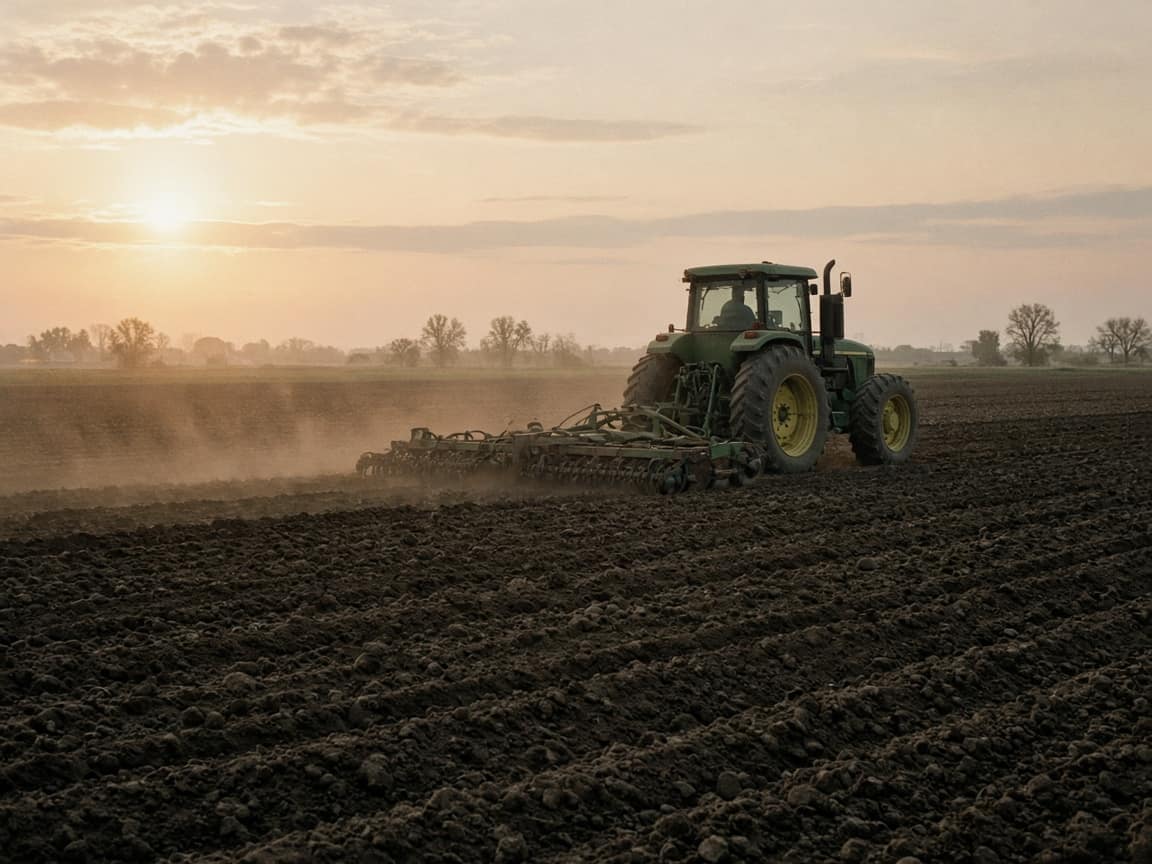
Tractor uses outside traditional farming
Solar vegetation management, airport grass cutting, and equestrian centers finance tractors with loaders and rotary cutters. Revenue may be service contracts rather than crop sales—lenders accept both when documented.
Four-wheel-drive and MFWD affect price and resale in wet climates; finance the traction you need instead of upsizing horsepower alone.
New vs used tractor financing
New tractors include powertrain warranties and sometimes bundled precision ag subscriptions—decide whether subscriptions belong in the equipment note.
Used tractors with hour meters on engines and PTO hours help underwriters; unknown hour history may cap terms.
Restored antique tractors rarely fit commercial lending programs focused on revenue equipment—seek specialty collectors’ lenders if needed.
Lease vs loan for tractors
Loans suit owners who run tractors until major clutch or transmission service, then trade with equity.
Leases may align to single harvest seasons or multi-year municipal mowing contracts with defined return standards.
Section 179 may benefit qualifying purchased tractors placed in service the same tax year, subject to IRS limits and business use tests—leases differ; model with our Section 179 calculator and your CPA.
Tractor lender documentation
Dealer invoice listing engine HP, cab type, loader model, and tire ballast.
Ag lenders may request crop plans or livestock counts; municipal borrowers provide contract awards.
Proof of storage and theft prevention for high-value compact tractors in suburban areas.
Compare three tractor finance quotes
Align quotes on cab vs open station and tire package—options swing price thousands of dollars.
Compare advance rates on used tractors with loader mounts welded on vs factory integrated.
Seasonal payment programs should be compared on total interest, not just winter skip count.
Review UCC filing practices if you also finance ag land equipment on the same entity—lien stacking matters to some banks.
PTO implements and loader bundles
Financing a loader with hay spears, grapples, or snow blowers on one invoice simplifies collateral but increases replacement cost if the loader is damaged—insurance should list attachment values.
PTO-driven implements wear independently of engine hours; lenders may not finance consumable blades or belts, but they will note if your revenue depends on a single large mower deck included in the package.
Vineyard and orchard tractors with narrow profiles cost more per horsepower—compare lender quotes using the same tire width and ballast so advance rates reflect the actual invoice, not a generic utility model.
Bi-directional mowing and road-side contracts may justify cab upgrades—if financed, list ROPS and cab HVAC on the invoice so collateral descriptions match insurance declarations.
Compare finance quotes after you finalize ballast and fluid-filled tire choices—both change delivered weight and insurable replacement cost.
Dealer demo tractors with remaining factory warranty may qualify for different advance rates than identical new-build orders—disclose demo status on each application.
Tractor payment calculator
Enter your own numbers. This is standard amortization math — not a quote. Fees, interim interest, and tax are not included.
- Amount financed
- —
- Estimated monthly payment (illustrative)
- Enter price and illustrative APR
Age at payoff
Many equipment lenders cap the tractor’s age when the loan ends — limits vary by lender, collateral type, and hours. LoanHelp does not publish lender caps here because they change and are not universal. Ask each provider: “What is the maximum age (or hour) limit at the last payment?”
If you finance in 2026 with a 60-month term, the final payment falls in 2030. A 2021 model would be about 9 years old at payoff.
This is a planning estimate only, not approval criteria. Used machines with high hours, missing maintenance records, or repowers may face shorter terms regardless of model year.
Common questions
- Are lawn tractors eligible for commercial financing?
- Programs target utility and ag-class tractors with identifiable VINs and commercial use. Sub-compact mowers may fall under different tiers—ask with your quote.
- Can I finance implements with the tractor?
- Implements on the same dealer invoice often collateralize together; separate used implements may need their own financing.
- How do lenders view mixed ag and contracting income?
- Diversified income can help if documented—schedule F plus 1099 contracting, for example. Explain seasonal overlap.
Related equipment
LoanHelp is not a lender. This page is general education—not an offer, rate quote, or approval guarantee.
Continue to application