Updated · LoanHelp editorial team · Editorial policy
Owners often pay the deductible, emergency drying or mitigation, and items a commercial policy may exclude before a claim pays. Document every invoice and photo, ask your insurer or agent about a partial or advance payment, and if cash still falls short compare a line of credit, working capital, or equipment financing on replacement quotes.
What you may pay before the claim pays
Commercial policies often require you to cover the deductible, emergency mitigation, and temporary repairs that keep damage from spreading. Some losses — spoilage, certain equipment, or ordinance upgrades — may fall outside coverage depending on endorsements. Check your policy and declaration pages; your agent can explain limits without LoanHelp interpreting the contract.
How to document costs for the claim
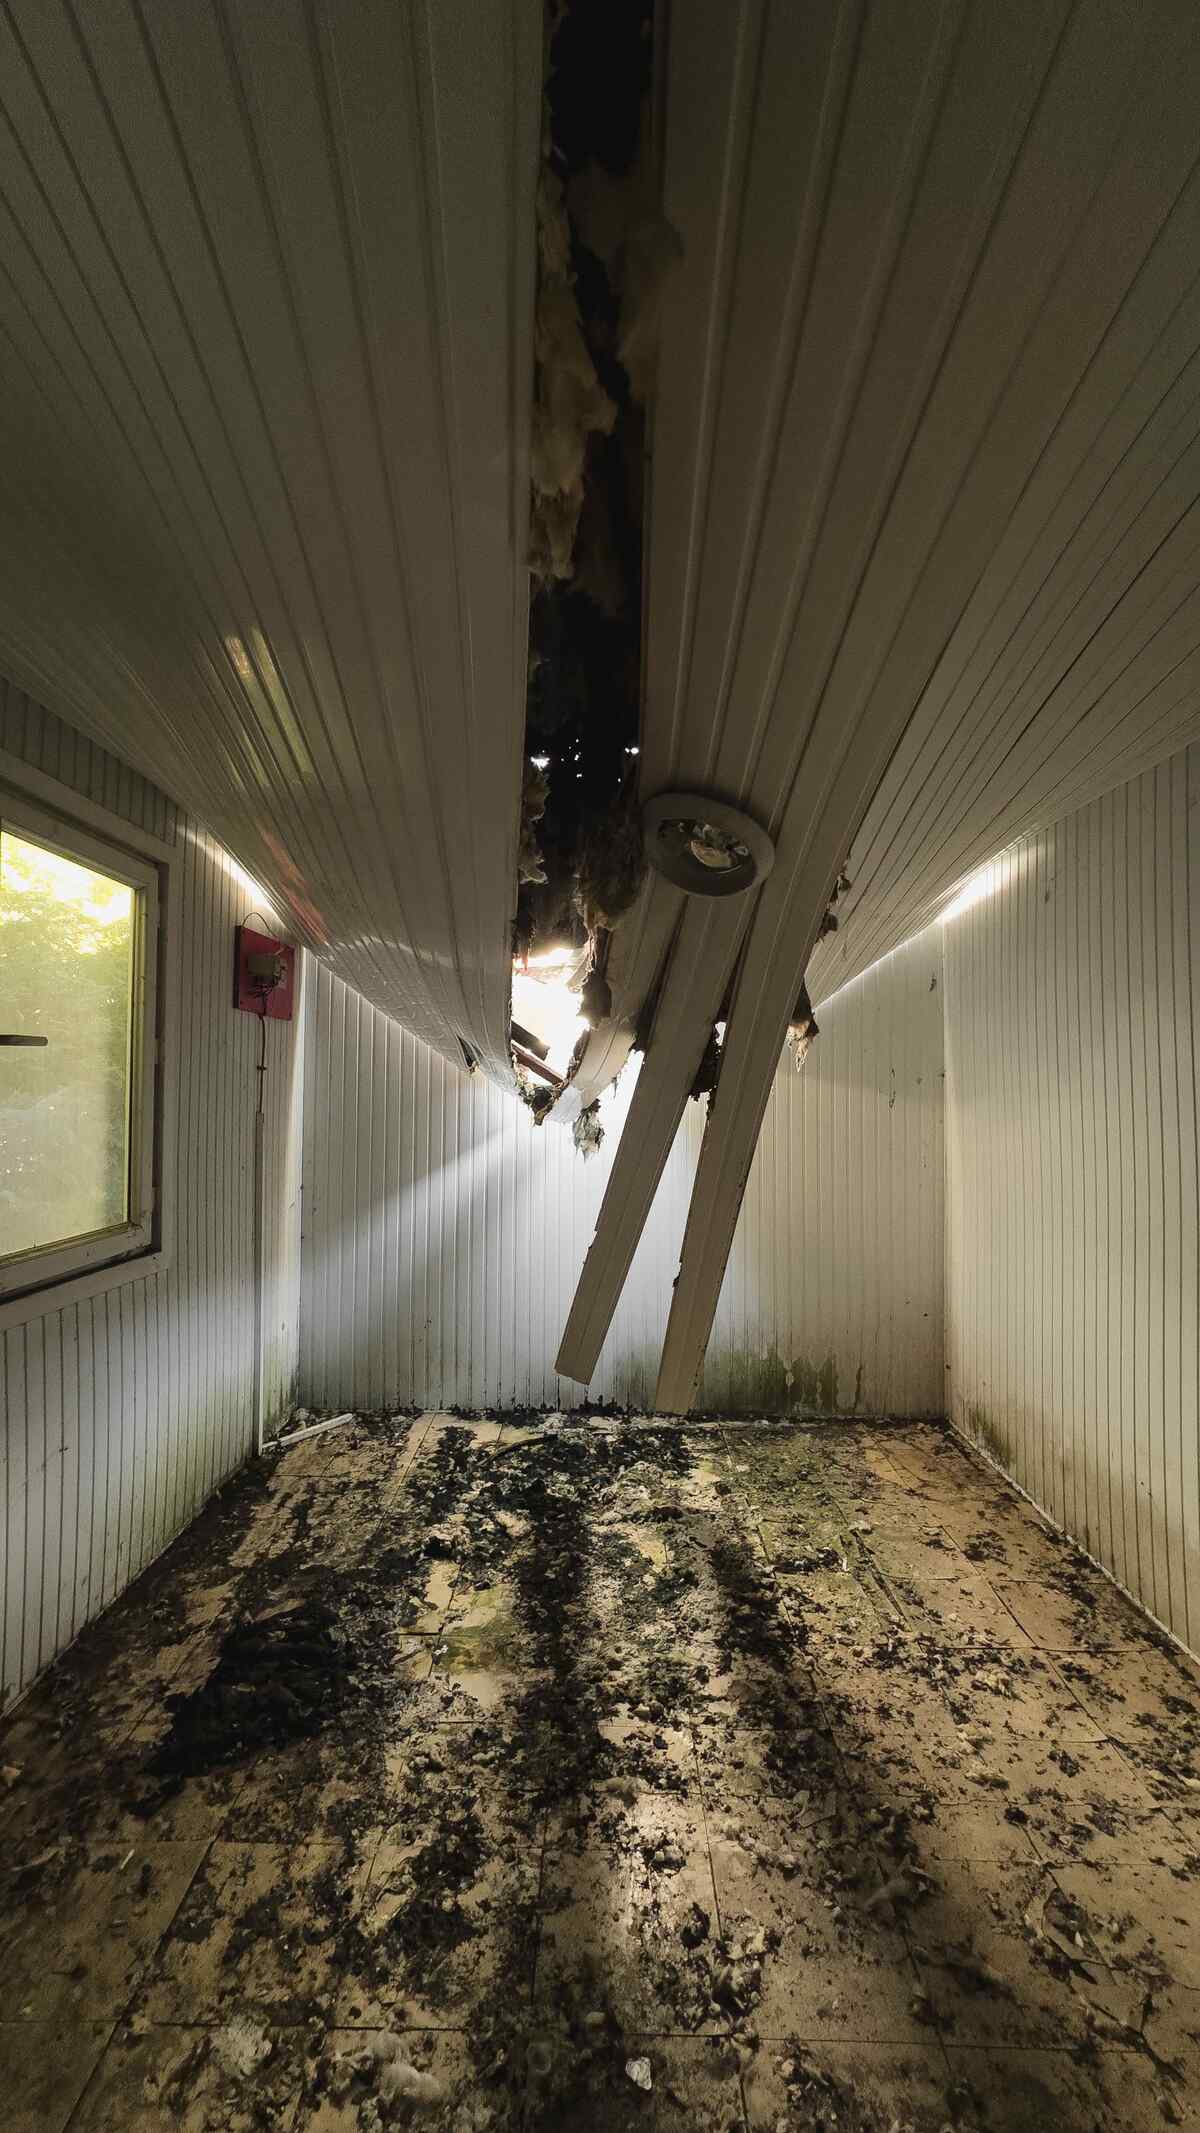
Photograph damage before cleanup, keep mitigation and contractor invoices, and log lost sales if your books track them. Ask the adjuster which formats they accept for photos, receipts, and revenue records. The NAIC consumer insurance hub links to filing and coverage topics; your state regulator may publish additional checklists.
Questions to ask your insurer or agent
- Can the carrier issue a partial or advance payment while repairs are underway?
- Does business interruption or extra-expense coverage apply to your loss — and what triggers it?
- What timeline should you expect for inspection, estimate approval, and payment?
- Do you need written approval before replacing equipment or opening walls?
Use the NAIC state insurance departments directory to reach your regulator, or read New York DFS guidance on filing a claim after a loss as an example of state-level claims guidance.
Bridge options while you wait
Compare how each path is repaid before you commit — totals vary, so use written offers. Use our cash gap calculator with your own numbers.
Recurring bills while you wait on a partial payment or settlement
Repayment: Draw and repay on your lender’s schedule — compare fees on written offers
Deductible, mitigation invoices, or payroll during a partial shutdown
Repayment: Fixed or periodic payments — totals vary, compare written offers
Replace coolers, kitchen lines, shop tools, or other equipment the policy may not fully cover
Repayment: Term tied to the replacement quote — compare to insurance proceeds
Supplier or contractor terms
Emergency vendor work when the contractor will invoice net terms
Repayment: Pay per invoice — confirm late fees before you commit
For a single-machine breakdown outside a storm claim, see how to pay for equipment repair. Walk-in cooler or freezer replacements may map to walk-in cooler financing.
If a federally declared disaster applies
When your county is in a declared disaster area, SBA disaster assistance may offer low-interest loans for physical damage or economic injury — terms are defined only on SBA.gov. LoanHelp is not affiliated with the SBA. For broader recovery planning, see Ready.gov business resources and our business financing after a disaster guide.
Related financing
Common questions
- Can I get a loan while waiting for an insurance payout?
- Some owners compare a line of credit, working capital, or equipment financing while a commercial claim is open. LoanHelp connects inquiries to our trusted financing partner separately from your insurer.
- What if the claim pays less than the repair cost?
- Check your policy for coverage limits, deductibles, and exclusions before you sign repair contracts. If a gap remains after the settlement, compare bridge options on total dollars from written offers rather than marketing copy.
- Does insurance cover lost income while my business is closed?
- Business interruption or extra-expense coverage depends on your policy wording and the cause of loss. Ask your agent or adjuster what is included and what documentation they need — LoanHelp does not interpret insurance contracts.
- Should I repair before the adjuster visits?
- Emergency mitigation to prevent further damage is often necessary, but major repairs may need adjuster approval. Photograph damage, keep mitigation receipts, and ask what your insurer requires before you remove equipment or open walls.
- What is business interruption coverage?
- It is a commercial property coverage that may address lost income or extra expenses after a covered loss, subject to policy terms. Your agent or state insurance department materials describe how to file — not LoanHelp.
- Will LoanHelp run a credit check when I submit an inquiry?
- LoanHelp does not perform a credit check when you submit an inquiry. Our trusted financing partner may request authorization for a credit inquiry later if you choose to move forward.